By Staff Reporter
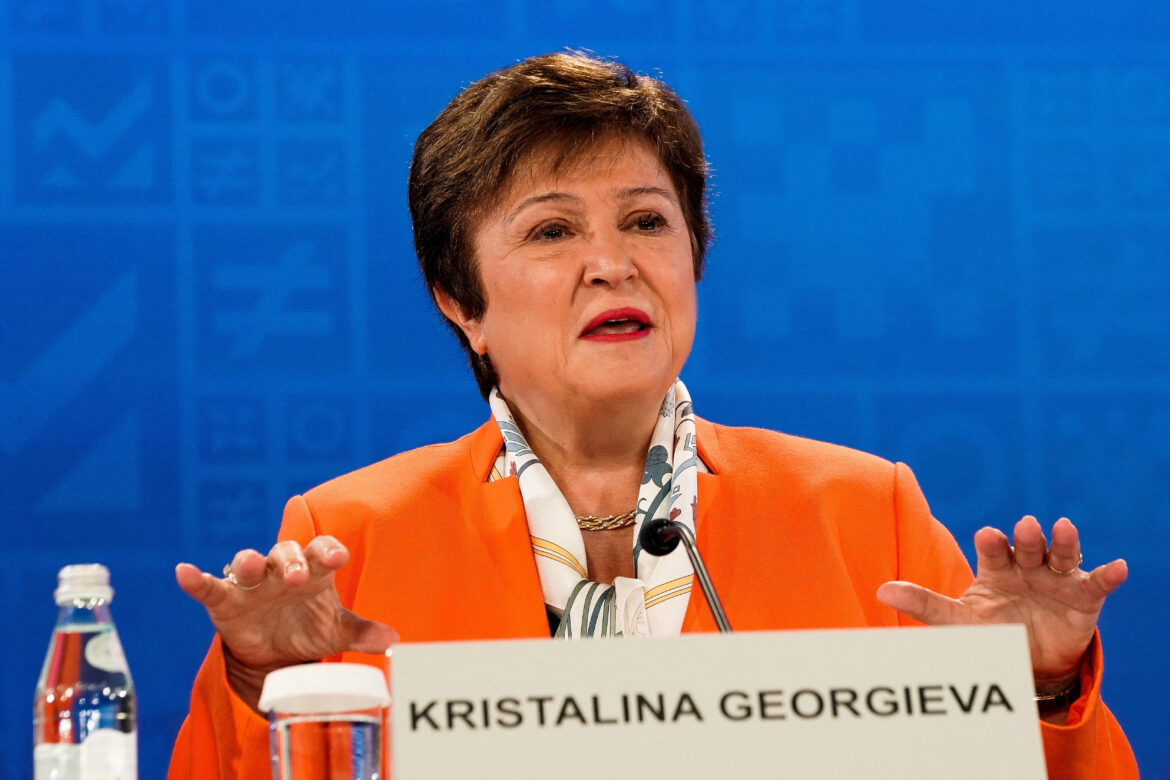
ISLAMABAD: The International Monetary Fund (IMF) Chief, Kristalina Georgieva, said on Thursday Pakistan has not yet reached the level of default and that the Fund is seeking confirmation from international partners to meet the country’s financing gap requirements.
Speaking at a news conference during the spring meeting of Bretton Woods Institutions in Washington D.C, Georgieva emphasized the need for a sustainable policy framework to avoid default risks and expressed hope that Pakistan would complete its ongoing IMF-funded program.
“We have been working very hard with the authorities in Pakistan to make sure that the policy framework is in place to avoid debt restructuring,” Georgieva said. “We expect not to get to a point when the debt of Pakistan becomes unsustainable. We are not there yet.”
Georgieva said the IMF is currently discussing additional support for Pakistan to complete the program.
“We are currently also discussing additional support for Pakistan in terms of financial assurances so we can complete the programme,” the Fund chief said.
“My hope is that in the context of what has already been agreed by the Pakistani authorities, we can successfully complete our current program.”
Meanwhile, a statement said finance minister Ishaq Dar held a Zoom meeting with Fund’s deputy managing director Antoinette Moniso Sayeh on Thursday.
During the meeting, the IMF’s deputy MD noted that Pakistan was yet to meet its external financing gap of $6 billion, out of which $3 billion would need to be financed before striking a staff level agreement.
State Bank of Pakistan governor Jameel Ahmed, who was in attendance at the IMF/WB Spring Meeting, stated that the UAE had shared a draft agreement for the provision of an additional $1 billion deposit in order to fulfil the requirement for signing SLA.
On the topic of cross fuel subsidy, the IMF was informed that it was just an idea floated by one relevant ministry and would only be implemented if all salient features of the scheme were agreed upon.
Pakistani authorities agreed with the IMF that the scheme looked good on paper but would be difficult to implement transparently.
The meeting provided an opportunity for Pakistan to advocate for the renewal of its $6.5 billion bailout package agreed upon in 2019, of which the government has been seeking a tranche of $1.1 billion since February.
The IMF tranche is critical for Pakistan as central bank reserves have fallen to critical levels, barely enough for four weeks of imports. Securing the tranche will also unlock other external financing avenues and help Pakistan avert a default on its obligations.
Pakistan is waiting for confirmation of an additional $1 billion in deposits from the United Arab Emirates before a staff-level agreement can be reached with the IMF.
The IMF has recently stated that assurance from multilateral donors and bilateral partners like China, Saudi Arabia, and the UAE to fund the balance of payment gap is a prerequisite for securing the bailout deal.
Last week, the IMF had informed Pakistani authorities that it has secured confirmation of the provision of $2 billion in additional deposits from the Kingdom of Saudi Arabia. Pakistan already sealed $2 billion rollover loan from all-weather ally China.
Copyright © 2021 Independent Pakistan | All rights reserved